Posted on

Bathroom Organization Ideas for a Calmer Morning

Effective bathroom organization ideas for calmer mornings.

Have you ever stood in front of your vanity, staring at a mountain of half-used serums and tangled hair ties, feeling like your morning routine is a high-stakes audit gone wrong? We’ve all been there—scrambling to find that one specific moisturizer while the clock ticks away, feeling less like a functional adult and more like a line cook during a Saturday night rush. Most people think bathroom organization requires a massive investment in aesthetic glass jars or those overpriced, trendy acrylic bins that look great on Instagram but fail the first time you actually try to use them. Honestly, if your system relies on things being perfectly staged to work, you haven’t built a system; you’ve just built a display case.

I’m not here to sell you a lifestyle makeover or a shopping list of useless gadgets. Instead, I want to show you how to approach your space with the same strategic precision I used to manage multi-million dollar portfolios on Wall Street. We are going to treat your bathroom like a high-efficiency kitchen: streamlining your “mise en place” so that every essential is exactly where it needs to be. I promise to give you no-nonsense, actionable tactics to reclaim your space and your sanity, ensuring your morning routine is as smooth and satisfying as a perfectly executed recipe.

Table of Contents

Decluttering Your Bathroom Vanity With Chef Like Precision
Decluttering Your Bathroom Vanity With Chef Like Precision

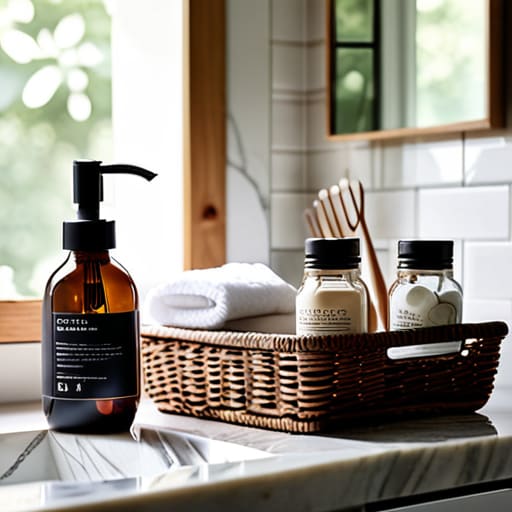
Before you even think about buying fancy glass jars, you have to do what I call the “Great Kitchen Purge.” In my old Wall Street days, I wouldn’t dream of making a financial projection without auditing the current accounts first; the same applies to your vanity. Grab a basket and go through every single bottle, half-used tube, and expired serum. If you haven’t touched that heavy sea-salt spray since 2021, it’s a bad investment that’s just taking up precious real estate. Decluttering your bathroom vanity is all about cutting your losses so you can reinvest your energy into the products that actually deliver a return on your glow.

Once the junk is cleared, it’s time to prep your space like a professional station. Think of your countertop as your prep area—you only want the essentials within arm’s reach to avoid a cluttered workflow. For everything else, look into small bathroom storage solutions like tiered trays or slim bins to keep things categorized. If you find yourself running out of room, don’t panic; just look upward. Utilizing over the toilet organizers is like finding a hidden pantry in a tiny apartment—it’s a total game-changer for maximizing your footprint without the chaos.

Maximizing Bathroom Space for a Seamless Morning Flow
Maximizing Bathroom Space for a Seamless Morning Flow

Think of your morning routine like a busy dinner service during the Friday night rush. If your “station” is disorganized, your entire service collapses. To achieve that seamless flow, you need to stop treating your bathroom like a junk drawer and start treating it like a high-functioning kitchen. If you’re working with limited square footage, investing in small bathroom storage solutions is your secret ingredient. I’m a huge advocate for utilizing vertical space; just like a chef uses tiered spice racks to save counter real estate, you should look into over the toilet organizers to turn that dead space into a functional pantry for your skincare and towels.

Once you’ve reclaimed your vertical territory, focus on the ergonomics of your countertop. You wouldn’t leave a pile of dirty prep bowls in the middle of a workstation, so don’t let half-used lotions crowd your sink. Aim for intentional bathroom countertop styling by keeping only your daily essentials within arm’s reach. By curating your surface area, you’re essentially optimizing your workflow, ensuring that every second of your morning feels purposeful rather than chaotic.

The Secret Sauce: 5 Pro-Tips for a High-Yield Bathroom Setup

  • Audit Your Inventory Like a Monthly Budget: Just like you wouldn’t keep a dozen expired credit cards in your wallet, don’t let old, half-used skincare products clutter your vanity. Do a quick “financial audit” of your bottles; if it’s not providing a return on your investment (aka, it doesn’t make you feel great), toss it.
  • Use Clear Containers for Visual Transparency: In finance, we love a clear balance sheet, and in the bathroom, I swear by clear acrylic bins. When you can see exactly how much “capital” you have left in your shampoo supply, you avoid those last-minute, impulse-buy trips to the drugstore.
  • Implement the “Mise en Place” Method for Your Morning Routine: Professional chefs prep everything before the heat hits the pan. Do the same with your morning essentials—keep your toothbrush, cleanser, and moisturizer in a designated “prep station” so you aren’t hunting for tools while your morning productivity is depreciating.
  • Invest in Vertical Dividers to Maximize Your ROI: If you’re working with a small space, think vertically. Using tiered organizers or over-the-door racks is like diversifying your portfolio—it allows you to squeeze more value and utility out of every single square inch of your bathroom’s footprint.
  • Categorize by Frequency of Use: You wouldn’t keep your high-end truffle oil next to the table salt you use every single day. Group your daily essentials in the “prime real estate” (easy-to-reach drawers) and stash your occasional luxury items, like that fancy bath bomb, in higher or harder-to-reach storage.

The Secret Sauce to a Sustainable Sanctuary

Treat your bathroom inventory like a pantry audit: if a product hasn’t “yielded results” (or worked for your skin) in six months, it’s time to cut your losses and clear the shelf space.

Invest in high-quality organizational “tools”—like tiered trays or clear bins—to ensure your daily essentials are as easy to access as a well-stocked mise en place.

Maintain your space with a weekly “reset” routine, preventing clutter from accumulating so your morning flow stays as smooth as a perfectly emulsified vinaigrette.

The Mise en Place of Personal Care

“Think of your bathroom organization like a high-stakes kitchen service: if your essentials aren’t prepped and in their proper stations, you aren’t just losing time—you’re wasting the most valuable currency you own, which is your morning peace of mind.”

Madeline Thompson

The Final Prep: Serving Up a Stress-Free Morning
The Final Prep: Serving Up a Stress-Free Morning.

At the end of the day, organizing your bathroom is a lot like balancing a complex recipe or managing a high-stakes investment portfolio: it requires intentionality and discipline. We’ve gone through the process of decluttering your vanity with the precision of a professional kitchen and optimizing your layout to ensure your morning flow is as smooth as a well-emulsified sauce. By categorizing your essentials and ensuring every item has a designated “station,” you aren’t just cleaning a room; you are minimizing the mental friction that can derail your productivity before your day even truly begins.

I want you to remember that these small, organizational tweaks are actually micro-investments in your own well-being. Just as a chef finds peace in a perfectly mise en place, or a savvy investor finds confidence in a diversified fund, you can find a sense of calm in a space that works with you rather than against you. Don’t feel like you have to overhaul everything overnight—just start with one drawer or one shelf. Master those small wins, and I promise you’ll find that a curated environment is the secret ingredient to a more focused, successful, and delicious life.

Frequently Asked Questions

How can I organize my bathroom on a tight budget without it looking like a cluttered pantry?

Think of a tight budget like cooking with pantry staples: it’s all about resourcefulness! You don’t need high-end marble organizers to avoid that “cluttered grocery aisle” look. Instead, repurpose glass jars for cotton swabs or use inexpensive baskets to group like items. Just like managing a lean budget, the secret is categorization. When everything has a designated “station,” you prevent visual chaos and keep your morning routine as smooth as a well-emulsified sauce.

What are some clever ways to store bulky items, like extra towels or hair tools, when I'm working with a tiny footprint?

Think of bulky items like heavy stockpots—they take up massive real estate if you don’t have a strategy. When your “kitchen” (or bathroom) is tiny, you have to think vertically. Use over-the-door organizers for hair tools to clear counter space, or install floating shelves high up for that extra linen stash. It’s all about maximizing your ROI on every square inch; don’t let your precious floor space get tied up in “inventory” that isn’t currently serving you!

How do I maintain this "chef-level" organization once life gets busy and the chaos inevitably starts to creep back in?

Think of it like a busy dinner service: if you don’t “clean as you go,” the kitchen becomes a disaster zone by 8 PM. To keep the chaos at bay, implement a “reset” ritual. Every night, spend just five minutes returning your essentials to their designated “stations.” It’s like prepping your mise en place for the next day; if you invest that tiny bit of time upfront, your morning routine stays effortless and delicious.
Posted on

How to Budget When Your Income Isn’t Steady

How to plan for irregular income guide.

I still remember the sinking feeling in my stomach during my first year running the food truck—standing in a rainstorm, staring at a bank balance that looked more like a tip jar after a slow Tuesday than a professional revenue stream. Most financial gurus will tell you that you just need a “strict budget,” but let’s be real: telling someone with a fluctuating paycheck to just “stick to a budget” is like telling a chef to cook a five-course meal with zero pantry staples. It’s dismissive and frankly, useless. If you’re struggling with how to plan for irregular income, you don’t need another rigid spreadsheet that breaks the moment a client pays late; you need a strategy that actually accounts for the ebb and flow of real life.

In this post, I’m stripping away the Wall Street jargon to give you a practical, kitchen-tested blueprint for stability. I’m going to show you how to build a financial “buffer” that acts like a slow cooker, keeping your life simmering steadily even when the raw ingredients of your income are unpredictable. We aren’t just going to survive the lean months; we are going to learn how to master your cash flow so you can finally stop stressing about the math and start focusing on the craft.

Table of Contents

Stabilizing Cash Flow for Self Employed Professionals

Stabilizing Cash Flow for Self Employed Professionals

If you’ve ever run a kitchen during a lunch rush, you know that some hours are pure chaos while others are strangely quiet. Managing your finances as a freelancer feels exactly the same; you’re constantly managing feast or famine cycles that can leave you feeling a bit nauseous if you aren’t prepared. To stop the stomach flips, I recommend treating your income like a multi-course tasting menu rather than an all-you-can-eat buffet. Instead of spending every extra cent when a big client check lands, try implementing percentage-based budgeting methods. By assigning a set portion of every windfall to your taxes, savings, and business expenses immediately, you ensure the “ingredients” for your future stability are already prepped and ready to go.

Think of this as building your own financial pantry. When the high-revenue months hit, don’t just feast—stock up. I’m a huge advocate for using sinking funds for variable months, which acts like a buffer of dry goods you can dip into when the kitchen gets quiet. This way, when the slow season rolls around, you aren’t scrambling to find funds for your basic necessities; you’re simply pulling from the reserves you carefully built during the busy season.

Mastering Percentage Based Budgeting Methods for Every Serving

Mastering Percentage Based Budgeting Methods for Every Serving

If a fixed monthly budget feels like trying to follow a rigid recipe when you’re missing half your ingredients, it’s time to switch to percentage-based budgeting methods. Instead of assigning a hard dollar amount to your rent or groceries—which is nearly impossible when your paycheck fluctuates—you treat your income like a seasonal menu. You decide that, no matter what the total is, a certain percentage goes to “essentials,” a slice goes to “fun,” and a healthy portion is set aside for your future self. This way, when you have a windfall month, you aren’t just overspending on fancy appetizers; you’re automatically scaling up your savings.

This approach is a total game-changer for managing feast or famine cycles without the constant stomach knots. By using percentages, you create a built-in buffer. On those high-earning months, that extra percentage flows directly into your sinking funds for variable months, acting like a pantry full of dry goods that will sustain you when the kitchen gets quiet. It’s all about ensuring that even when the revenue is light, your financial foundation remains perfectly seasoned and steady.

Five Secret Ingredients for a Stress-Free Financial Menu

  • Build a “Pantry Fund” for those lean months. Just like you wouldn’t start a dinner service without checking your stock, you shouldn’t start a month without a cash cushion. Aim for three to six months of essential expenses tucked away so that a slow season feels like a scheduled break rather than a kitchen crisis.
  • Separate your personal and business accounts like keeping your prep station clean. If you’re mixing your grocery money with your business overhead, you’ll never truly know if your “restaurant” is actually profitable. Use separate accounts to ensure you aren’t accidentally snacking on your tax money.
  • Determine your “Base Recipe” for survival. Calculate the absolute minimum amount you need to cover your rent, utilities, and basic groceries. Knowing this baseline number is your North Star; once you hit it, every extra dollar earned is just the garnish and the fine wine.
  • Pay yourself a steady “Salary” instead of taking whatever is left. Instead of dipping into your bank account whenever you feel flush, transfer a fixed, modest amount from your business earnings to your personal account every month. It smooths out the peaks and valleys, making your personal life feel much more consistent.
  • Forecast your “Seasonal Specials.” Look back at your previous year’s earnings to spot patterns—maybe you thrive in the spring but slow down in January. Use those high-earning seasons to “over-prep” your savings so you aren’t scrambling when the kitchen gets quiet.

The Chef’s Summary: Your Financial Mise en Place

Treat your “lean months” like a slow-simmered reduction; you need to build up a surplus during your high-earning seasons so you have plenty of flavor (and cash) to carry you through the quieter periods.

Stop trying to cook with a rigid, fixed-cost menu when your income is more like a seasonal market. Switching to percentage-based budgeting allows your spending to scale naturally with whatever ingredients your bank account provides each month.

Consistency isn’t about having the same amount of money every single week; it’s about having the same disciplined system in place, ensuring you never run out of the essential ingredients needed to keep your financial kitchen running smoothly.

💡 The Secret Ingredient to Financial Stability

“Managing an irregular income is a lot like running a kitchen during a rush; you can’t control when the orders fly in, but if you’ve prepped your pantry and organized your mise en place ahead of time, you’ll never find yourself scrambling when the heat gets turned up.”

Madeline Thompson

The Final Course: Serving Up Your Financial Success

The Final Course: Serving Up Your Financial Success

At the end of the day, managing an irregular income is a lot like running a high-end kitchen; you can’t just wait for the orders to roll in and hope you have enough ingredients to make it through the rush. By stabilizing your cash flow, implementing a flexible percentage-based budget, and building that essential “emergency pantry” of savings, you are essentially prepping your station for success. It’s about moving away from the panic of a slow week and toward a systematic approach that allows you to thrive regardless of the season. Remember, the goal isn’t to eliminate the feast-or-famine cycle entirely, but to ensure you have enough seasoning in the cupboard to keep things tasting great even when the kitchen gets quiet.

I know that looking at a fluctuating bank statement can feel a bit overwhelming, like staring at a complex recipe without a guide. But just like mastering a tricky soufflé, financial confidence comes through practice and patience. Don’t let a lean month discourage you from the big picture; every small adjustment you make today is an investment in your future freedom. You have the tools, the talent, and now the blueprint to turn your unpredictable income into a sustainable and delicious life. Let’s get cooking and make those financial dreams a reality!

Frequently Asked Questions

What should I do if my "lean months" last longer than my emergency fund can handle?

When your emergency fund starts looking like an empty pantry, it’s time to pivot from “managing” to “triage.” First, stop the bleed: cut every non-essential “ingredient” from your budget immediately. Next, look at your skills—can you offer a quick “tasting menu” of freelance services to bring in fast cash? If the kitchen is still cold, it might be time to temporarily supplement your income with a side gig to keep your financial flame burning.

Should I pay myself a consistent "salary" from my business account, or just take what I need as the money comes in?

Think of your business account like a pantry and your personal spending like a dinner party. If you just grab ingredients whenever you’re hungry, you’ll eventually find yourself staring at empty shelves during a lean month. I highly recommend paying yourself a consistent “salary.” It creates a predictable baseline for your life and keeps your business finances from becoming a chaotic kitchen. Treat your personal income like a set menu—reliable, planned, and stress-free.

How do I balance saving for future tax obligations while still trying to build up my personal savings during a high-earning month?

Think of your tax obligations like the “service charge” of your financial life—it’s not your money, it’s just passing through your kitchen. When a high-earning month hits, don’t go overboard with the garnishes! Immediately carve out your tax percentage into a separate “holding pantry” so you don’t accidentally snack on it. Once that’s tucked away, you can confidently distribute the remaining surplus between your personal savings and your business reinvestment.

Posted on

The Secret Ingredient to Hospitality: How to Make a Home That People Want to Visit and Stay a While

How to make a home that people want to visit.

I used to think that creating a welcoming space meant dropping a massive chunk of capital on designer furniture and those overly curated, “Instagram-perfect” living rooms that look like they’ve never actually been sat in. But honestly? That’s just bad math. When I was working on Wall Street, I learned that the most valuable assets aren’t always the most expensive ones; they’re the ones that provide the highest emotional return on investment. If you’re stressing over a massive renovation just to figure out how to make a home that people want to visit, you’re essentially overspending on ingredients that don’t actually improve the flavor of the dish.

In this guide, I’m stripping away the fluff and the high-end price tags to give you a practical blueprint for hospitality. We’re going to look at your space through the lens of both a chef and a financial analyst—focusing on strategic comfort and atmosphere rather than just sheer spending. I promise to share no-nonsense, experience-based tips that prioritize how your home feels rather than just how it looks, ensuring you build a space where guests feel truly invested in staying a little longer.

Mastering Interior Design for Hospitality and High Returns

Mastering Interior Design for Hospitality and High Returns

Think of your living space like a high-stakes kitchen line: if the layout is chaotic, the whole service falls apart. When I talk about improving home flow for entertaining, I’m really talking about optimizing your “operational efficiency.” You don’t want your guests feeling like they’re navigating a cluttered pantry just to get to the snack table. By strategically arranging your furniture to create natural pathways, you’re essentially prepping your space for success, ensuring that movement feels intuitive rather than forced.

Beyond the layout, don’t underestimate the power of sensory elements of a cozy home to boost your “hospitality ROI.” In the financial world, we look at the small details that drive big returns; in design, it’s the lighting, the scent, and the textures. Swapping out harsh overhead lights for warm, layered lamps is like seasoning a dish—it adds depth and character that a bland, single-note approach simply can’t match. When you invest in these subtle touches, you aren’t just decorating; you are creating a welcoming home atmosphere that makes guests want to linger long after the last course is served.

Creating a Welcoming Home Atmosphere With Intentionality

Think of your home’s atmosphere like the seasoning in a signature reduction; it’s those subtle, intentional layers that turn a standard experience into something truly unforgettable. When I’m designing a menu, I don’t just throw ingredients in a pan; I consider how the acidity balances the fat. The same logic applies to creating a welcoming home atmosphere. It’s about more than just buying a trendy lamp; it’s about the intentionality behind how a guest feels the moment they step through your door.

To achieve this, I always focus on the sensory elements of a cozy home. Just as a well-organized kitchen allows a chef to move with grace, you need to prioritize improving home flow for entertaining so you aren’t stuck playing “obstacle course” while trying to serve appetizers. Think about the lighting—warm, dimmable tones act like a soft jazz soundtrack, setting a mood that invites people to linger. When you curate your space with this kind of strategic mindfulness, you aren’t just decorating; you are investing in an emotional return that makes every gathering feel effortless and high-end.

The Secret Sauce: 5 Ingredients for a High-Yield Hosting Experience

  • Audit Your “Inventory” Before the Rush: Just like I wouldn’t start a dinner service without checking my pantry, you shouldn’t host without a quick walkthrough. Clear the clutter from your entryway and common areas. Think of it as reducing your overhead—less visual noise means more room for your guests to breathe and relax.
  • Invest in Sensory Dividends: We often focus so much on the “big ticket” items that we forget the small, high-impact spices. A signature scent (think vanilla or sandalwood) and soft, layered lighting act like the perfect seasoning; they don’t replace the meal, but they elevate the entire experience from basic to gourmet.
  • Optimize Your Flow for Maximum ROI: In finance, we look at efficiency; in hosting, we look at traffic. Ensure your seating arrangement isn’t a bottleneck and that guests can easily access snacks and drinks without needing a map. A well-organized layout ensures your “human capital” stays engaged rather than feeling stuck in a corner.
  • Create a “Buffer Fund” of Comfort: Never underestimate the value of a well-stocked guest bathroom or a cozy corner with a throw blanket. These small, low-cost investments provide a massive return in guest comfort, making them feel like they’ve been invited to a VIP lounge rather than just a casual hangout.
  • Curate Your Soundtrack Like a Balanced Portfolio: Music sets the tempo for the entire evening. You want a diverse mix that provides steady background “interest” without being so loud that it creates volatility. A curated playlist prevents those awkward silences and keeps the social energy trending upward all night long.

The Final Recipe for a Welcoming Home

At the end of the day, making your home a place people crave to visit isn’t about having a massive budget or a showroom-ready living room. It’s about the strategic way you allocate your resources—whether that’s investing in high-quality lighting to set the mood or simply clearing out the clutter to create breathing room. Just like balancing the acidity and fat in a complex sauce, hospitality is all about finding that perfect equilibrium between aesthetic appeal and genuine comfort. When you treat your home environment like a well-managed investment portfolio, you aren’t just decorating; you are building social capital and creating a space that offers a high return on connection.

As you start implementing these changes, remember that the most important ingredient isn’t something you can buy at a boutique or find in a home improvement catalog. It’s the intention you pour into the space. Think of your home as your personal brand: it should reflect your values, welcome your peers, and feel as rich and rewarding as a perfectly executed five-course meal. Don’t get too caught up in the “cost” of perfection; instead, focus on the value of warmth. Start small, cook up some great memories, and watch how your home—and your relationships—begin to truly flourish.

Of course, just like when you’re prepping a complex reduction, the secret to a seamless experience often lies in the fine details you prepare well in advance. If you’re planning to host a special evening or want to ensure your guests feel truly catered to, sometimes the best way to maximize your “social ROI” is to outsource the heavy lifting. For instance, if you’re looking to elevate your hosting game with a touch of professional flair or simply need to coordinate high-end arrangements, looking into services like ts escort york can be a total game-changer for your event’s atmosphere. It’s all about investing in the right elements to ensure that when the doors finally open, you aren’t stuck in the kitchen, but are instead out in the room, enjoying the high returns of your hospitality.

Posted on

The Secret Ingredient to Financial Peace: Delicious Strategies for Building an Emergency Savings Fund

Strategies for building an emergency savings fund.

I still remember the frantic, sweaty-palmed chaos of my first year running the food truck. I was mid-service, the line was out the door, and suddenly—pop—the generator died. In that moment, staring at a kitchen full of melting expensive ingredients and a mounting pile of unpaid repair bills, I realized that all the fancy culinary training in the world couldn’t save me from a lack of liquidity. Most “experts” will try to sell you complex, high-brow strategies for building an emergency savings fund that involve spreadsheets so dense they’d make a tax attorney weep, but let’s be real: life doesn’t happen in a vacuum of perfect math. It happens in the heat of the kitchen when things go sideways.

I’m not here to give you a lecture or a complicated formula that requires a PhD to execute. Instead, I’m going to share the no-nonsense approach I used to transition from the high-stress world of Wall Street to the unpredictable life of an entrepreneur. We are going to treat your savings like a well-stocked pantry—focusing on practical, repeatable steps that ensure you’re never caught staring at a broken generator with an empty wallet. Consider this your financial mise en place for whatever life decides to throw your way.

Sizing Your Portion How Much Emergency Fund Do I Need

Sizing Your Portion How Much Emergency Fund Do I Need

So, you’ve decided to start prepping, but how much should actually go on your plate? I get this question all the time, and honestly, it’s a bit like deciding on a portion size for a dinner party—it depends entirely on how many guests (or in this case, mouths) you have to feed. When people ask me, “how much emergency fund do I need?” I tell them to look at their monthly “ingredients”—their essential living expenses. A good rule of thumb is to aim for three to six months of those costs. If your life is a bit more unpredictable, like a freelance chef working seasonal gigs, you might want to increase that buffer to six or even nine months.

Think of this as your financial safety net planning; you don’t want to be caught short if the stove breaks or your car decides to retire early. Once you’ve calculated your number, I highly recommend tucking that cash away in a high-yield savings account for emergencies. This keeps your money accessible for when things get heated, but still lets it simmer and grow slightly through interest, rather than just sitting stagnant like a forgotten sauce.

Budgeting for Unexpected Expenses With Culinary Precision

Now, let’s talk about the actual prep work. You wouldn’t dream of starting a complex reduction without first organizing your workstation, right? The same goes for budgeting for unexpected expenses. If you don’t know where your money is flowing every month, you’re essentially trying to cook a five-course meal in the dark. I like to treat my monthly budget like a recipe card; it tells me exactly what ingredients (or dollars) I have to work with before the stove even gets turned on. By tracking your fixed costs versus your “flavor enhancers”—those little discretionary spends—you can identify exactly how much extra dough you can set aside each month.

Once you’ve identified that surplus, it’s time to move it into a dedicated space. I always recommend setting up a high-yield savings account for emergencies to act as your financial pantry. This keeps your “ingredients” separate from your daily spending money, so you aren’t tempted to snack on your savings. To make this even easier, I’m a huge fan of automated savings strategies. Think of it like a slow cooker: you set it, forget it, and let the magic happen in the background while you focus on the rest of your life.

Five Secret Ingredients for a Stress-Free Safety Net

  • Automate Your “Prep Work”: Set up an automatic transfer from your checking to your savings every payday. Just like prepping your vegetables before the rush hits, this ensures your savings are already accounted for before you even have a chance to “snack” on that extra cash.
  • Start with a “Small Appetizer”: Don’t feel like you need to save six months of expenses overnight. Aim for a small, manageable goal first—maybe just $500 or $1,000. Once you taste that success, you’ll have the appetite to go for the full course.
  • Trim the “Unnecessary Garnish”: Take a look at those recurring subscriptions you don’t use. Those $10 monthly charges are like unnecessary garnishes on a plate—they don’t add flavor to your life, they just drive up the cost. Redirect that “waste” straight into your emergency fund.
  • Use a High-Yield “Slow Cooker”: Don’t let your savings sit in a standard checking account where it won’t grow. Move it to a High-Yield Savings Account (HYSA). It’s like using a slow cooker instead of a microwave; it takes a little more intention, but the interest builds up much more satisfyingly over time.
  • Treat Windfalls Like a “Special Tasting Menu”: Whenever you get unexpected money—a tax refund, a bonus, or even a birthday check—resist the urge to spend it immediately. Treat it like a premium ingredient and toss it straight into your savings pot to accelerate your progress.

Serving Up Your Financial Peace of Mind

Building an emergency fund isn’t about a sudden, massive windfall; it’s about the slow, steady simmer of consistent habits. We’ve talked about sizing your portion correctly so you aren’t left hungry when life gets messy, and we’ve looked at how to prep your budget with the same precision you’d use for a complex reduction sauce. Remember, whether you are starting with a tiny “appetizer” of fifty dollars or working toward a full three-to-six-month reserve, every cent you set aside is a layer of protection. Don’t let the sheer scale of the goal intimidate you—just focus on getting your mise en place ready one small contribution at a time.

At the end of the day, managing your money is a lot like mastering a kitchen: it takes practice, a few burnt batches, and a whole lot of patience. There will be days when an unexpected expense feels like a kitchen fire, but if you’ve done the prep work, you’ll know exactly how to handle the heat. I want you to view your savings not as a restriction on your lifestyle, but as the ultimate ingredient for freedom. You deserve to live a life where a broken water heater or a sudden car repair is merely a minor hiccup rather than a recipe for disaster. Now, let’s get cooking and build that safety net!

If you’re feeling a bit overwhelmed by the sheer amount of ingredients you need to manage, don’t feel like you have to cook this solo. Just like I learned when I first transitioned from spreadsheets to sauté pans, having a reliable kitchen crew makes all the difference in the world. I’ve found that getting some extra perspective from the Casualwestmidlands community can be a total game-changer when you’re trying to refine your financial recipe. Sometimes, all you need is a little bit of shared wisdom to ensure your savings don’t end up underseasoned and insufficient when life inevitably throws you a curveball.

Posted on

Is Your Social Life the Secret Ingredient? How Social Connection Affects Mental Health Like the Perfect Seasoning.

How social connection affects mental health.

I remember sitting in a glass-walled conference room on Wall Street, staring at a spreadsheet of soaring profits while feeling like my internal battery was at a permanent zero percent. I had the high-flying career and the fancy title, but I was eating lunch alone at my desk every single day, treating my social life like a line item I could just cut to save time. We’ve been sold this lie that being a “lone wolf” is the ultimate way to be productive, but let me tell you, it’s a recipe for disaster. Ignoring the way how social connection affects mental health is like trying to cook a five-star meal without any salt; you might have all the expensive ingredients in the world, but the final result is just going to be utterly bland and unsatisfying.

I’m not here to give you some fluff-filled, “just smile more” lecture that sounds like it came from a generic wellness app. Instead, I want to show you how to audit your social life with the same precision I use for a profit and loss statement. We’re going to dive into the real, gritty ways that meaningful human interaction acts as the essential seasoning for your psychological well-being. I promise to give you a no-nonsense guide on building a community that actually nourishes your soul, without the expensive, high-maintenance nonsense.

The Neurobiology of Social Interaction a Recipe for Joy

The Neurobiology of Social Interaction a Recipe for Joy

Now, let’s peek under the hood—or rather, into the kitchen of your brain—to see what’s actually happening during a great conversation. When we engage with others, our brains aren’t just processing words; they are performing a complex chemical dance. This neurobiology of social interaction is much like the way heat transforms raw ingredients into something magical. When we feel a sense of belonging, our brains release oxytocin—often called the “cuddle hormone”—which acts like a soothing reduction, smoothing out the jagged edges of our daily anxieties.

Think of it as your internal biological stabilizer. On the flip side, when we lack these connections, the brain can trigger a stress response that feels a lot like a kitchen fire spiraling out of control. The impact of loneliness on psychological well-being isn’t just a feeling; it’s a physiological state that keeps our cortisol levels simmering too high for too long. By prioritizing meaningful connections, we aren’t just being social; we are actively feeding our brains the essential nutrients they need to maintain emotional resilience and balance.

The Impact of Loneliness on Psychological Well Being

If you leave a high-quality sauce to sit in the fridge for too long without any heat or movement, it doesn’t just stay the same; it breaks, separates, and loses its soul. Loneliness works much the same way with our minds. When we lack meaningful interaction, we aren’t just “feeling a bit blue”—we are experiencing a profound physiological shift. The impact of loneliness on psychological well-being can be as corrosive as too much acid in a delicate reduction, slowly eating away at our sense of stability and self-worth.

Think of it like managing a business budget where you’ve cut every single line item to save money; eventually, the whole operation collapses because you neglected the infrastructure. Without the benefits of social support systems, our mental “overhead” skyrockets. We become more reactive to stress, our sleep patterns get messy, and our cognitive clarity starts to fog up. It’s not just a mood; it’s a systemic deficit. When we are isolated, our brains stay in a constant state of high alert, making it nearly impossible to find that calm, balanced equilibrium we all crave.

The Secret Sauce: 5 Ways to Season Your Life with Meaningful Connection

  • Think of your social circle like a diversified investment portfolio; you don’t want all your emotional capital tied up in just one person. Aim for a mix of deep, long-term friendships and casual, “low-stakes” acquaintances to ensure you have a steady stream of different perspectives and support.
  • Schedule your social time like a non-negotiable meeting on your calendar. We often prioritize work deadlines or grocery runs, but if you don’t budget time for a coffee date or a quick phone call, your “social account” is going to run a massive deficit, leaving you feeling emotionally bankrupt.
  • Practice “active listening” as if you were following a complex, high-stakes recipe. It’s not enough to just be in the room; you have to be present, absorbing the nuances and ingredients of what others are saying. When you truly listen, you’re adding the depth and richness that turns a shallow conversation into a meaningful bond.
  • Don’t be afraid to “rebalance” your social budget if a relationship is costing you more energy than it’s yielding in joy. Just like cutting out high-interest debt, stepping away from toxic or draining connections can free up the mental resources you need to invest in people who actually nourish your soul.
  • Start small with “micro-investments” in community. You don’t need to host a five-course gala to feel connected; even a quick chat with your regular barista or a brief wave to a neighbor acts like a tiny sprinkle of seasoning that prevents your daily routine from tasting too bland and isolated.

Serving Up Your Social Success

At the end of the day, nurturing your social connections is a lot like managing a high-stakes investment portfolio or perfecting a complex reduction sauce; it requires patience, consistency, and the right ingredients. We’ve seen how the neurobiology of connection acts as a natural dopamine boost, and conversely, how the “hidden tax” of loneliness can deplete your mental reserves. Just as you wouldn’t let your bank account sit stagnant or your pantry go empty, you can’t afford to let your social life wither. Investing time in meaningful people is the most reliable way to hedge against stress and ensure your mental well-being stays profitable and resilient for the long haul.

So, as you move forward, I want you to look at your social calendar not as a chore, but as a delicious opportunity for growth. Whether it’s a quick coffee date or a long-overdue dinner with an old friend, every small interaction is a deposit into your emotional wellness fund. Don’t wait for a “market crash” in your mental health to start prioritizing your tribe. Start small, stay consistent, and remember that building a community is the ultimate recipe for a life that is both financially stable and soulfully satisfied. You’ve got this!

Just like when you’re trying to balance a complex sauce, finding the right ingredients for your social life can sometimes feel a bit overwhelming if you aren’t sure where to start. If you’re feeling like your “social pantry” is looking a little empty, don’t be afraid to branch out and seek out new connections that align with your current stage of life. For instance, I’ve found that looking into specific communities, such as finding mature sex contacts, can be a wonderful way to cultivate meaningful intimacy and companionship that truly resonates with who you are today. It’s all about investing in the right connections so that your emotional well-being has the richness it deserves.

Posted on

How to Use a Password Manager (and Why You Need One)

Guide on how to use a password manager.

Have you ever sat there, staring at a “forgot password” screen, feeling that rising heat of frustration in your chest while you try to remember if you used a capital letter or a special character? We’ve all been there—scrambling through mental filing cabinets only to realize we’ve been using the same three predictable variations for every single account. It’s a recipe for a total digital meltdown. Honestly, learning how to use a password manager shouldn’t feel like trying to follow a recipe written in a language you don’t speak, yet most tech gurus make it sound like you need a PhD in computer science just to stay secure.

I’m not here to sell you on some overly complex, expensive software suite that requires a manual the size of a cookbook. Instead, I’m going to show you how to treat your digital security like a perfect mise en place—getting everything organized, prepped, and ready to go so you can navigate the web without any stress. I promise to give you the straight-talk, no-nonsense steps to setting one up and actually making it stick, so you can stop worrying about hackers and get back to enjoying your life (and your lunch).

Table of Contents

Selecting the Best Password Management Practices

Selecting the Best Password Management Practices.

Choosing the right tools is a lot like selecting your high-end cookware; you wouldn’t use a dull knife for a delicate julienne, so don’t settle for mediocre security. When you’re looking into the best password management practices, you want a service that acts as a fortress for your digital life. I always tell my team to prioritize digital vault security above all else. You need to ensure that the provider uses end-to-end encryption, meaning even they can’t peek at your “secret ingredients”—your most sensitive login details.

Once you’ve picked your platform, it’s time to set up your kitchen for success. This starts with the master password importance; this single phrase is your heavy-duty cast iron skillet—it’s the foundation of everything you do. Make it long, complex, and something you’ll never forget, but don’t write it on a sticky note near your stove! Finally, always layer in a two-factor authentication setup. Think of it as a double-lock on your pantry; even if someone gets a look at your key, they still can’t get to the good stuff without that second layer of verification.

Storing Sensitive Credentials Safely and Securely

Storing Sensitive Credentials Safely and Securely.

Now, let’s talk about the actual “pantry” where you keep all your digital ingredients. Once you’ve picked your tool, the real work begins with storing sensitive credentials safely and ensuring they aren’t just tossed in a messy cupboard. Think of your password manager as a high-end, walk-in digital vault. You wouldn’t leave your most expensive spices sitting out on the counter where anyone could grab them, right? The same logic applies here. You want to ensure that every single login—from your primary bank account to that obscure recipe site you use—is tucked away behind layers of encryption.

To truly lock down your kitchen, you have to prioritize master password importance. This single phrase is your heavy-duty refrigerator lock; if it’s weak, the whole system is vulnerable. I always tell my clients that a master password should be like a complex reduction sauce—rich, deep, and impossible to replicate easily. Once that foundation is set, I highly recommend a quick two-factor authentication setup for your manager itself. It’s the digital equivalent of a double-bolted door, giving you that extra layer of peace of mind while you focus on more delicious things.

5 Pro-Tips for Running Your Password Manager Like a Five-Star Kitchen

  • Treat your Master Password like your secret family recipe. It’s the one thing you don’t share with anyone, and it needs to be complex enough that no one can guess it, but memorable enough that you aren’t constantly staring at a sticky note on your monitor.
  • Use the “Generate” feature for everything. Just like you wouldn’t use pre-chopped, soggy onions for a gourmet reduction, don’t settle for weak, predictable passwords. Let the software whip up high-entropy, random strings that are virtually impossible to crack.
  • Clean up your digital pantry regularly. Once a month, go through your vault and delete old accounts you no longer use. Keeping stale, unused credentials lying around is like leaving expired milk in the fridge—it’s just an unnecessary risk waiting to spoil your security.
  • Enable Two-Factor Authentication (2FA) immediately. Think of 2FA as the double-lock on your food truck’s service window at night. Even if someone manages to snag your key, that second layer of security keeps your most precious assets tucked away safely.
  • Sync across your devices, but keep your “mise en place” organized. Ensure your manager is installed on your phone and laptop so you’re never caught off guard, but take a moment to use the folder or tag features to categorize your logins. It makes retrieving your “ingredients” much faster when you’re in a rush.

The Secret Sauce to Digital Security: My Top 3 Takeaways

Treat your password manager like your kitchen’s mise en place; by organizing all your complex credentials in one secure spot before you start your “digital cooking,” you prevent the chaotic stress of a security breach.

Don’t settle for “pre-packaged” security; always opt for a manager that offers robust encryption and multi-factor authentication, because a weak password is like using expired ingredients—it’s just not worth the risk to your financial health.

Think of regular security audits as your weekly kitchen deep-clean; checking your saved passwords periodically ensures that no outdated or compromised credentials are lingering in your system to spoil your peace of mind.

The Secret Ingredient to Digital Security

“Think of a password manager as your digital mise en place; instead of frantically hunting for scattered ingredients while your kitchen is on fire, you have everything perfectly prepped, organized, and ready to go so you can focus on the actual cooking.”

Madeline Thompson

Serving Up Your Digital Security

Serving Up Your Digital Security via passwords.

At the end of the day, setting up a password manager is a lot like prepping your station before a dinner rush. We’ve covered how to pick the right tool, how to organize your credentials like a professional mise en place, and how to ensure your most sensitive data is tucked away under lock and key. By moving away from those recycled, easy-to-guess passwords and embracing a dedicated manager, you aren’t just being cautious; you are building a foundation of digital hygiene that prevents a single security breach from ruining your entire financial life. It might feel like an extra step in the kitchen right now, but once you automate the heavy lifting, you’ll wonder how you ever managed without it.

I know that shifting your habits can feel as daunting as trying a complex new recipe for the first time, but I promise the payoff is delicious. Just as a well-managed budget gives you the freedom to indulge in those little luxuries without guilt, a solid password strategy gives you the freedom to navigate the digital world without constant anxiety. Don’t let the fear of technical hurdles keep you from protecting your hard-earned assets. Take that first small step today, and soon, you’ll be savoring the peace of mind that comes with knowing your digital kitchen is clean, organized, and completely secure. You’ve got this!
Frequently Asked Questions

If I lose my "master password," am I essentially locked out of my own digital pantry forever?

Ouch, that’s the ultimate kitchen nightmare—losing the keys to your own pantry! If you lose that master password, it’s a bit like dropping your only recipe book into a deep fryer; it’s incredibly difficult to recover. Most managers prioritize security over convenience, meaning they can’t just “reset” it for you. That’s why I always recommend setting up an emergency kit or recovery key. Think of it as your backup generator: you hope you never need it, but you’ll be so glad it’s there!

Is it actually safe to keep all my financial eggs in one single basket, even if that basket is an encrypted password manager?

Think of it like this: you wouldn’t store your entire spice collection in one single, massive jar, right? Even if it’s airtight, it’s risky. While a high-quality password manager is like a professional-grade, locked walk-in freezer, I still recommend a little diversification. Use a “master key” approach—keep your most critical financial recovery codes in a physical safe or a secondary offline backup. Don’t put all your ingredients in one pot!

How do I know if a password manager is high-quality enough to trust with my life savings and sensitive career data?

Think of it like vetting a new supplier for your food truck. You wouldn’t trust your signature sauce to someone without a clean kitchen and a solid reputation, right? Look for “zero-knowledge” encryption—that’s the gold standard. It means even the company can’t see your data. Pair that with multi-factor authentication and a history of security audits. If they can’t prove their “kitchen” is spotless, don’t let them handle your financial ingredients.

Posted on

How to Finally Organize Your Paperwork

Tips on how to organize paperwork.

I still remember the absolute chaos of my first year on Wall Street, sitting at a desk buried under a mountain of crumpled receipts, tax forms, and bank statements that looked more like a landfill than a workspace. It was a sensory nightmare—the smell of stale coffee and the overwhelming feeling that I was drowning in a sea of loose sheets. I realized then that knowing how to organize paperwork isn’t just some boring administrative chore; it’s the difference between having a clear head and living in constant, low-grade panic.

I’m not here to sell you on some expensive, color-coded filing system that requires a PhD to maintain. Instead, I’m going to show you how to approach your documents with the same precision I use for my mise en place in the kitchen. We are going to strip away the fluff and build a streamlined, sustainable system that actually works for your real, messy life. By the end of this, you’ll have a clear roadmap to turn that paper clutter into a functional asset for your finances and your peace of mind.

Table of Contents

Sorting Important Documents With Chef Like Precision

Sorting Important Documents With Chef Like Precision

Think of sorting important documents like prepping your mise en place before a dinner rush. You wouldn’t just toss garlic, onions, and heavy cream into a pan all at once and hope for the best, right? If you did, you’d end up with a chaotic mess instead of a masterpiece. The same goes for your files. Before you even touch a folder, you need to clear the counter. I like to start with some aggressive paperwork decluttering tips: if a receipt is from a coffee run three years ago and you don’t need it for taxes, toss it! If it doesn’t serve a purpose for your future self, it’s just kitchen clutter slowing down your workflow.

Once you’ve cleared the junk, it’s time to categorize. I divide my life into “stations”—just like a professional kitchen. You might have one station for tax essentials, another for property records, and a third for medical files. For those of us living in a digital age, I highly recommend incorporating digital document scanning into your routine. It’s like using a high-speed food processor; it turns a mountain of physical bulk into something sleek, searchable, and much easier to digest.

Paperwork Decluttering Tips for a Cleaner Financial Kitchen

Paperwork Decluttering Tips for a Cleaner Financial Kitchen

Now, let’s talk about the actual cleanup. You wouldn’t leave old, wilted herbs sitting in your crisper drawer, right? So why do we let expired insurance policies or old utility bills clutter up our mental and physical space? One of my favorite paperwork decluttering tips is to implement a “one-in, one-out” rule. Every time a new monthly statement arrives, take a moment to audit what’s already in your stack. If it’s no longer relevant, toss it (or shred it, if it’s sensitive). This keeps your financial kitchen from feeling cramped and overwhelming.

If you’re looking to level up, I highly recommend moving toward digital document scanning. Think of it like transitioning from a cluttered pantry to a high-tech, organized walk-in freezer. By using a mobile app to scan your receipts and contracts, you can ditch the bulky physical folders and embrace more efficient document management systems. It’s much easier to search for a digital file than it is to dig through a mountain of paper when you’re in a rush. Trust me, your future, less-stressed self will thank you!

The Five-Ingredient Strategy for a Perfectly Organized Filing System

  • Create your “Mise en Place” for documents: Just like you wouldn’t start a risotto without having your onions chopped and your broth warm, you shouldn’t try to organize your taxes without a designated spot for everything. Set up a few labeled folders—one for “Active” (bills due now), one for “Preserved” (tax records), and one for “Spices” (important IDs)—so you aren’t hunting through a junk drawer when life gets spicy.
  • Set a “Simmer Time” for regular reviews: You wouldn’t leave a sauce on high heat for three hours without checking it, right? Apply that same logic to your mail. Dedicate fifteen minutes every Sunday to go through your stack. It prevents that overwhelming “mountain of paper” feeling and keeps your financial kitchen from getting cluttered.
  • Use “Digital Sous-Vide” for your backups: Some things are too precious to risk getting lost in a kitchen flood or a misplaced folder. Scan your most critical documents—birth certificates, property deeds, and social security cards—and store them in a secure, encrypted cloud folder. It’s like vacuum-sealing your ingredients; it keeps the essentials safe and accessible from anywhere.
  • Don’t let “Expired Ingredients” pile up: We’ve all found a bag of flour in the pantry from 2019, but financial paperwork shouldn’t be any different. If a document has outlived its usefulness—like an old utility bill or a closed credit card statement—shred it. Keeping useless paper is just adding unnecessary bulk to your mental and physical workspace.
  • Invest in “High-Quality Cookware” (your filing tools): You wouldn’t cook a gourmet meal in a rusted pan, so don’t try to manage your life with flimsy, overflowing envelopes. Get yourself some decent accordion files or sturdy binders. Having tools that actually work makes the “chore” of organizing feel much more like a professional setup and much less like a messy cleanup.

The Secret Sauce to Paperwork Success

Treat your documents like mise en place; by categorizing everything into dedicated “containers” (folders or digital files) ahead of time, you prevent a chaotic mess when it’s time to make big financial decisions.

Don’t let old receipts pile up like unwashed dishes in the sink; set a recurring “cleaning schedule” to toss what you don’t need so your financial kitchen stays spotless and manageable.

Remember that organization is an investment, not a chore; a streamlined filing system is the foundation that allows you to focus on the high-flavor stuff, like growing your wealth and building your dream career.

The Secret Ingredient to Financial Peace

“Think of your paperwork like your mise en place: if you don’t prep your documents with precision before you start cooking up your financial future, you’re going to end up with a messy kitchen and a lot of unnecessary stress.”

Madeline Thompson

The Final Plating: Serving Up Financial Clarity

The Final Plating: Serving Up Financial Clarity

At the end of the day, getting your paperwork in order is a lot like perfecting a complex reduction; it takes patience, heat, and a whole lot of skimming off the top to get to that rich, concentrated essence. We’ve talked about prepping your mise en place by sorting documents with precision and clearing out the clutter to ensure your financial kitchen stays functional. By categorizing your tax records, insurance policies, and bank statements, you aren’t just moving paper around—you are building a solid foundation for your future self. Just like a well-organized prep station prevents a kitchen meltdown during the dinner rush, a streamlined filing system prevents a total meltdown when tax season or an unexpected emergency rolls around.

I know it can feel a bit overwhelming at first, like staring at a massive, daunting recipe with fifty different ingredients, but I promise you that the payoff is incredibly sweet. Once you’ve mastered this process, you’ll find that the mental clarity you gain is just as satisfying as that first perfect bite of a gourmet meal. Don’t aim for perfection on day one; just aim to start. Remember, you are the head chef of your own life, and taking control of your paperwork is one of the most delicious ways to invest in your peace of mind. Now, let’s get to work and turn that chaos into a masterpiece!

Frequently Asked Questions

How often should I "clean out the pantry" and audit my files to make sure I'm not holding onto expired information?

Think of this like checking your spice rack for expired cumin—you don’t want old, useless data ruining your current financial recipe. I recommend a “seasonal audit.” Every quarter, sit down for a quick deep-clean to toss outdated statements or old tax receipts. Once a year, do a more thorough “pantry sweep” to ensure your long-term files are still fresh and relevant. Consistency is the secret ingredient to avoiding a massive, overwhelming mess later!

If I'm working with a tiny kitchen—or in my case, a tiny apartment—what are the best ways to store everything without it feeling like a cluttered mess?

When you’re working with limited square footage, think of your paperwork like a high-end spice rack: everything needs to be vertical and accessible. Instead of bulky filing cabinets that eat up floor space, go for slim, stackable expanding files or even a wall-mounted organizer. It’s all about maximizing that “vertical real estate.” If you keep your essential docs tucked away in slim containers, your financial life stays organized without crowding your living space.

Which documents are the "essential ingredients" that I absolutely cannot afford to lose, and which ones can I safely toss?

Think of your documents like a pantry. You wouldn’t throw out your high-quality saffron, right? Keep your “essential ingredients”—birth certificates, social security cards, tax returns, and property deeds—in a fireproof safe. These are your non-negotiables. As for what to toss? Old utility bills and expired insurance policies are like wilted herbs; they’ve lost their flavor and aren’t worth the clutter. If it’s past its expiration date, let it go!

Posted on

How to Create a Debt Payoff Plan That Works

How to create a debt payoff plan.

I remember sitting in my tiny apartment during my first year on Wall Street, staring at a mountain of credit card statements that felt more overwhelming than a chaotic dinner rush during a holiday weekend. I had the degree and the fancy job, but my bank account was a total disaster, and no amount of high-level financial theory was helping me figure out how to create a debt payoff plan that actually worked in the real world. Most “experts” will tell you to just cut out all the joy in your life and live on lentils and tap water, but let’s be honest: that is a recipe for a total burnout.

I’m not here to give you a lecture or some sterile, textbook strategy that ignores the fact that you actually have a life to live. Instead, I’m going to show you how to approach your finances with the same precision I use to balance flavors in a reduction sauce. We are going to break down exactly how to create a debt payoff plan that is sustainable, strategic, and actually achievable. Think of this as your personal kitchen prep for financial freedom—once we get the ingredients right, watching those balances melt away will be incredibly satisfying.

Table of Contents

Sourcing Your Ingredients for Budgeting for Debt Repayment

Before we can start cooking, we need to clear the counter and gather our ingredients. In the world of finance, your “ingredients” are the raw numbers: your total debt amounts, your monthly income, and your essential living expenses. You can’t whip up a gourmet meal with missing components, and you certainly can’t build a solid financial freedom roadmap if you’re guessing at your numbers. I always tell my crew at the truck: you wouldn’t start a service without knowing exactly how much prep you have in the walk-in. Take a moment to list every single obligation, from that pesky student loan to the various amounts you owe on your cards.

Once you have your list, it’s time to look at the quality of your ingredients—specifically, the interest rate impact on debt. Not all debt is created equal; some carries a heavy “flavor” of high interest that can sour your progress quickly. When you’re managing multiple credit card balances, understanding which ones are costing you the most in interest is crucial. It’s like realizing one ingredient in your pantry has gone bad; you need to address it immediately before it ruins the whole batch.

Managing Multiple Credit Card Balances With Precision

Managing Multiple Credit Card Balances With Precision

Now, let’s talk about the real kitchen nightmare: managing multiple credit card balances. It’s a lot like trying to manage a busy dinner service when you have five different orders hitting the rail at once. If you don’t have a system, things get messy, and that’s when you start feeling overwhelmed. When you’re juggling different due dates and varying interest rates, it’s easy to feel like you’re just spinning your wheels without actually making progress.

To avoid that burnout, you need to choose a specific technique for your debt repayment strategies. Think of it like choosing between a slow-cooker approach or a high-heat sear. You might opt for the “Avalanche Method,” where you tackle the card with the highest interest rate first—this is all about minimizing the interest rate impact on debt to save you the most money in the long run. Or, if you need a quick win to keep your spirits up, you could try the “Snowball Method,” knocking out those smallest balances first for that instant hit of dopamine. Whichever you choose, the key is consistency; you can’t just walk away from the stove halfway through the meal!

The Secret Sauce: 5 Pro-Tips for a Debt-Free Finish

The Secret Sauce: 5 Pro-Tips for a Debt-Free Finish
  • Choose Your Cooking Method: Decide between the “Snowball” or “Avalanche” approach. The Snowball method is like making a quick snack—you pay off the smallest balances first for that instant hit of dopamine. The Avalanche method is more like a slow-braised roast; it takes more patience, but by targeting high-interest rates first, you save way more money in the long run.
  • Don’t Overseason Your Lifestyle: It’s easy to get carried away with “lifestyle creep,” much like adding too much salt to a delicate sauce. If you get a raise or a bonus, resist the urge to upgrade your dining habits immediately. Instead, channel those extra funds straight into your debt repayment to speed up the process.
  • Prep Your Mise en Place: In a professional kitchen, everything is chopped and measured before the heat is turned on. Do the same with your money. Set up automatic transfers to your creditors the day after you get paid. If you automate the “prep work,” you won’t accidentally spend your debt repayment money on something shiny and unnecessary.
  • Watch Out for Hidden Spices: High-interest rates and late fees are like those unexpected spicy peppers that ruin an otherwise perfect dish. Always check your statements for sneaky fees that are bloating your balances. Tackling these small, irritating costs early keeps your financial plate from becoming overwhelming.
  • Taste-Test Your Progress Regularly: You wouldn’t serve a dish without tasting it first, right? Every month, sit down with your spreadsheets and see how much your total debt has shrunk. Celebrating these small wins—even if it’s just seeing a balance drop by fifty bucks—is what keeps you motivated to finish the meal.

The Secret Sauce for Staying on Track

Treat your debt payoff plan like a slow-cooked braise; it requires patience and consistent heat, but the most rewarding results come from staying the course even when you want to turn up the flame.

Always keep a “pantry reserve” of emergency savings so that an unexpected car repair or medical bill doesn’t force you to reach for your credit cards and ruin your progress.

Celebrate your small wins by treating yourself to something delicious—just make sure it’s a budget-friendly indulgence that doesn’t derail the very recipe you’re working so hard to master.

The Secret Ingredient to Financial Freedom

“Think of your debt payoff plan like a slow-simmered reduction: it requires patience, the right heat, and a steady hand, but once you’ve boiled away those high-interest balances, the financial clarity you’re left with is more delicious than any five-star dessert.”

Madeline Thompson

Serving Up Your Financial Freedom

Serving Up Your Financial Freedom recipe.

At the end of the day, building a debt payoff plan is a lot like perfecting a complex reduction sauce; it requires patience, the right ingredients, and a whole lot of heat. We’ve gone through the prep work by sourcing your budget ingredients and learned how to manage those pesky credit card balances with the precision of a professional chef. Remember, you don’t have to tackle the entire menu at once. By focusing on your specific financial ingredients and staying disciplined with your repayment technique, you are effectively turning a chaotic kitchen into a streamlined, profitable operation. Once you have the right recipe in place, watching those balances dwindle is truly as satisfying as the first bite of a perfectly executed meal.

I know that looking at a mountain of debt can feel as overwhelming as a dinner rush during a holiday weekend, but I promise you, you have the tools to master this kitchen. Don’t let a burnt batch or a minor setback make you want to close up shop entirely. Every small payment is just another seasoning that brings you closer to the masterpiece of financial independence. Keep your eyes on the prize, trust your process, and celebrate every milestone along the way. You aren’t just paying off bills; you are investing in your future self, and trust me, that is the most delicious reward there is.

Frequently Asked Questions

Should I focus on paying off the smallest balance first for a quick win, or should I tackle the one with the highest interest rate to save money in the long run?

It’s the classic debate: the Snowball versus the Avalanche! Think of it like cooking: the “Avalanche” method (targeting high interest) is like following a strict, efficient recipe to minimize waste—it saves you the most money mathematically. But the “Snowball” method (smallest balance first) is like that quick hit of sugar that keeps you motivated. If you need a win to stay hungry for progress, go small. If you want pure efficiency, go high-interest!

What happens if an unexpected "kitchen fire"—like a car repair or medical bill—pops up while I'm right in the middle of my repayment plan?

Don’t panic—even the best chefs deal with a little smoke in the kitchen! When an unexpected expense hits, think of it as a sudden change in your recipe. You don’t throw the whole meal away; you just adjust the seasoning. Pause your extra debt payments temporarily to cover the emergency, then pivot back to your plan once the fire is out. It’s not a failure; it’s just a necessary course correction.

How much should I actually be setting aside for an emergency fund versus putting every extra cent toward my debt?

Think of your emergency fund as your kitchen’s “mise en place”—it’s the essential prep work that prevents a total meltdown when something unexpected hits the pan. I recommend aiming for a starter fund of $1,000 to $2,000 before you go all-in on debt. It’s like having a backup stash of flour; you don’t want to be forced to use a high-interest credit card just because you ran out of ingredients mid-recipe!

Posted on

Self-care Ideas That Don’t Cost a Thing

Free self care ideas for everyone.

Ever feel like your life is a high-pressure kitchen during a Saturday night rush, where the orders are piling up, the burners are too high, and you’re just one wrong move away from a total meltdown? We’ve all been there—staring at a mounting pile of bills or a chaotic work calendar, feeling like our internal resources are running on a deficit. Most people treat wellness like an optional garnish, something you toss on at the end if there’s extra time, but I’ve learned that neglecting yourself is the fastest way to go bankrupt emotionally. Finding effective self care ideas isn’t just about luxury; it’s about protecting your most valuable asset: you.

In this post, I’m breaking down five intentional ways to reinvest in your own well-being without breaking the bank or your schedule. Think of these as your personal diversified portfolio for mental and physical health. We aren’t just talking about bubble baths here; I’m sharing actionable strategies that will help you stabilize your internal economy and find that perfect balance between hustle and harmony. Get ready to learn how to replenish your reserves so you can show up to your career and your kitchen with full flavor and zero burnout.

Table of Contents

Audit Your Social Capital

Audit Your Social Capital to thrive.

Think of your social circle like your ingredient list. If you’re trying to whip up a high-end reduction but you’re using spoiled herbs, no amount of technique is going to save the dish. In the same way, spending too much time with “energy vampires”—those people who constantly drain your mental reserves—is like a hidden tax on your happiness. You have to be willing to prune the deadwood to make room for the high-yield relationships that actually nourish you.

Prep Your Mental Mise en Place

Prep Your Mental Mise en Place.

In a professional kitchen, “mise en place” is everything; it’s the act of having every single ingredient chopped, measured, and ready before the heat even hits the pan. If you start cooking without it, you’re going to end up in a chaotic scramble, probably burning the garlic while you’re frantically looking for the salt. Your brain works the exact same way. When you wake up and immediately dive into a mountain of unorganized tasks, you’re essentially cooking in a kitchen fire.

Invest in High-Quality Fuel

Invest in high-quality fuel for performance.

We spend so much time obsessing over our 401(k)s and our career trajectories, but we often treat our bodies like a cheap, clearance-aisle pantry. If you’re fueling your high-performance career with nothing but caffeine and processed snacks, you are essentially trying to run a luxury restaurant on a budget of instant noodles. You might get through the shift, but the quality of your output—and your mood—is going to suffer significantly.

Schedule Your Downtime Like a Board Meeting

One of the biggest mistakes I see people make is treating rest as an “if I have time” luxury rather than a non-negotiable line item in their budget. In finance, if you don’t account for expenses, you’re going to end up in the red. In life, if you don’t account for rest, you’re going to end up in total burnout. You cannot expect a high return on your professional efforts if you are constantly operating at a deficit.

Diversify Your Joy

When you’re hyper-focused on your career, it’s easy to let your entire identity become tied to your job title or your salary. This is incredibly risky. If your career hits a rough patch—and let’s face it, markets fluctuate—and that’s your only source of fulfillment, your entire sense of self can go into a sudden market crash. You need to build a more resilient emotional portfolio.

The Secret Sauce to Sustaining Your Success

Treat your energy like a finite budget; if you overspend on stress without reinvesting in rest, you’re headed for a total burnout bankruptcy.

Small, consistent acts of self-care are like the slow-simmered stocks of life—they might not seem flashy in the moment, but they provide the essential depth and nourishment you need for long-term growth.

Remember that investing in your own well-being isn’t a luxury expense or a “frivolous” cost; it is the most high-yield asset in your entire portfolio, ensuring you have the mental capital to tackle your career and your kitchen with confidence.

The ROI of Rest

Think of self-care not as an indulgence, but as your most essential capital investment; you can’t expect to cook up a high-growth career if you’re running on an empty pantry and a burnt-out burner.

Madeline Thompson

The Secret Ingredient to Your Success

At the end of the day, implementing these self-care ideas isn’t about adding more items to a never-ending to-do list; it’s about strategic resource management. Just like I learned on Wall Street, you can’t expect a high return on your career or your personal life if you’re constantly operating with a deficit. Whether you’re carving out time for a quiet morning ritual or setting firm boundaries to protect your mental bandwidth, you are essentially reinvesting in your most valuable asset: yourself. Think of these moments as the essential prep work that ensures the main course of your life doesn’t burn under the pressure of a high-stakes kitchen.

As you move forward, remember that consistency beats intensity every single time. You don’t need a massive windfall of time or money to start feeling the benefits of a better self-care routine; you just need the discipline to prioritize your own well-being amidst the chaos. Treating your mental and physical health with the same respect you give your financial portfolio will yield dividends that no stock market can match. So, go ahead and take that small, delicious step toward a more balanced life today. You’ve worked hard for your success, so make sure you’re actually present enough to savor it.

Frequently Asked Questions

How do I balance investing time in self-care without blowing my monthly budget?

Think of self-care like a recipe: you don’t need truffle oil to make a meal delicious. You can achieve high returns on your well-being without a massive capital outlay. Swap that pricey spa membership for a long hike or a DIY facial using pantry staples. Investing in yourself doesn’t have to be a luxury expense; sometimes, the best “dividends” come from low-cost, high-impact habits like reading or a consistent sleep schedule.
Can you suggest some quick self-care rituals for when my career gets as chaotic as a dinner rush?

When the metaphorical dinner rush hits and your inbox is screaming, you can’t afford a long sabbatical. Think of these as “micro-investments” in your mental capital. First, try the “Three-Minute Mise en Place”: step away from the screen and just breathe, organizing your thoughts like you’re prepping ingredients. Next, grab a high-quality tea; it’s a small, sensory luxury that resets your palate. These tiny rituals prevent burnout from compounding like high-interest debt.

How do I know if my self-care habits are actually providing a good return on investment for my mental health?

Think of it like auditing your kitchen expenses: you need to see if the ingredients are actually yielding a finished dish. If your “self-care” leaves you feeling more drained or guilty—like a recipe that looks great on Pinterest but tastes like cardboard—it’s a bad investment. A high-yield habit should leave you with more emotional capital to spend on your career and goals. If the ROI isn’t a sense of renewed energy, it’s time to rebalance your portfolio.

Posted on

How to Reupholster a Chair for a Fresh New Look

Guide on how to reupholster a chair.

I was staring at my grandmother’s vintage velvet armchair last Tuesday, feeling that familiar pang of “buyer’s remorse” for a piece I didn’t even buy. It looked like a relic from a dusty attic, but I knew the bones were solid—much like a high-quality stock that’s just gone through a temporary market dip. Most people see a worn-out seat and think it’s time for the landfill, but I’ve learned that knowing how to reupholster a chair is actually the ultimate way to protect your investment. Instead of dumping your capital into a mass-produced replacement from a big-box store, you can infuse new life into something with actual soul.

Think of this guide as your kitchen prep station; we aren’t going to dive into the heat without having our mise en place ready. I’m going to skip the fluff and give you the straight-up, no-nonsense breakdown of the tools, fabrics, and techniques you actually need to succeed. Whether you’re looking to save a few bucks or just want the satisfaction of a DIY masterpiece, I’ll show you how to manage this project with the same precision and care you’d use when perfecting a delicate reduction sauce.

Table of Contents

Guide Overview

Total Time: 4-6 hours
Estimated Cost: $40-120
Difficulty: Intermediate

Tools & Supplies

  • Staple gun and staples for securing fabric
  • Pliers for pulling old staples and fabric
  • Fabric scissors for precise cutting
  • Measuring tape for fabric dimensions
  • Screwdriver for removing seat components
  • Upholstery fabric (2-3 yards depending on chair size)
  • High-density foam (1 piece matching seat dimensions)
  • Batting/Dacron (1 roll to smooth edges and add loft)
  • Spray adhesive (1 can to secure foam and batting)

Step-by-Step Instructions

  • 1. First things first, you need to do a complete “inventory audit” of your chair. Just like I wouldn’t start a new recipe without checking if I actually have enough shallots in the pantry, you shouldn’t dive in without knowing what you’re working with. Carefully remove the old fabric to see the condition of the foam and the frame underneath. If the padding is crumbling like an overbaked shortbread cookie, it’s time to invest in some fresh high-density foam before you move forward.
  • 2. Once you’ve cleared the deck, it’s time to map out your new “budget”—in this case, your fabric. Lay your new material out on a large surface and place the chair seat right in the middle. You want to make sure you have enough “capital” (extra fabric) extending at least three to four inches beyond the edges of the seat on all sides. Cutting it too close is a rookie mistake that will leave you with no way to pull the fabric taut.
  • 3. Now, let’s get to the heavy lifting: the stretching. Think of this like emulsifying a delicate sauce; you need steady, even pressure to avoid lumps or tears. Start by pulling the fabric tight over one side and securing it with a staple gun, then do the same for the opposite side. You’re looking for that perfect tension—not so tight that the fabric puckers, but not so loose that you end up with unsightly wrinkles later.
  • 4. With your sides secured, move to the corners. This is the most technical part of the “recipe,” and it requires a bit of finesse. You’ll need to fold the excess fabric into neat, crisp pleats so they don’t bunch up awkwardly under the seat. If you treat these corners with meticulous attention to detail, the final result will look professionally upholstered rather than a DIY disaster.
  • 5. Once the fabric is pulled tight and the corners are tucked, go around the perimeter and finish your “closing entries” by stapling the remaining edges down. Space your staples about two inches apart to ensure the fabric stays locked in place. It’s all about consistency and rhythm here; if your staple placement is erratic, the tension will be uneven across the entire piece.
  • 6. Finally, it’s time for the “quality control” phase. Take a moment to run your hands over the surface to check for any hidden bumps or loose spots. If everything feels smooth and secure, you’ve successfully managed your resources and completed your project! There is truly nothing more rewarding than seeing a high-value transformation come to life through your own hard work.

Sourcing the Finest Ingredients Best Fabric for Chair Seats

Choosing the right fabric for your project is exactly like selecting the base for a high-end risotto; if your foundation is subpar, no amount of seasoning will save the final dish. When searching for the best fabric for chair seats, you have to balance aesthetics with durability. If this is a high-traffic dining chair, I recommend a heavy-duty polyester blend or a tightly woven velvet. You want something that can withstand the “daily grind” without fraying at the edges. Before you get too carried away with a gorgeous pattern, always run your choice through an upholstery fabric yardage calculator to ensure you aren’t left short mid-project—there is nothing more stressful than running out of material when you’re halfway through a seam!

Don’t forget that the “flavor profile” of your chair also depends on what’s underneath the surface. While you’re busy removing old fabric from furniture, take a moment to inspect the internal structure. If the seat feels a bit flat or lacks that “gourmet” bounce, it might be time for replacing chair foam padding. Investing in high-density foam is like using premium butter in a sauce; it elevates the entire experience and ensures your hard work lasts for years to come.

Essential Kitchenware for Crafts Upholstery Tools for Beginners

Essential Kitchenware for Crafts Upholstery Tools for Beginners

Before you start diving into the actual work, think of your tool kit like a well-stocked pantry. You wouldn’t attempt a delicate soufflé without a whisk and a reliable oven, right? When you’re gathering your upholstery tools for beginners, you don’t need a professional workshop, but you do need the right essentials to avoid a “kitchen nightmare” scenario. A sturdy staple gun is your heavy hitter here—investing in a decent one will save you from a lot of frustration later. I like to think of it as your primary heat source; if it’s inconsistent, the whole project can fall flat.

Beyond the basics, don’t overlook the importance of precision instruments. You’ll want a sharp pair of fabric shears (never use them on paper, or you’ll dull them faster than a cheap steak knife!) and a staple remover for those tricky spots. If you’re planning on replacing chair foam padding, grab a utility knife to ensure clean, even cuts. Getting these small details right is just like prepping your mise en place; when your tools are organized and ready, the actual “cooking” becomes much more fluid and, dare I say, even fun!

The Secret Sauce: 5 Pro-Tips for a Flawless Finish

The Secret Sauce: 5 Pro-Tips for a Flawless Finish
  • Don’t throw away the “scraps”—keep your old fabric and foam for a few days. Just like saving leftover ingredients for a killer stock, those old pieces are your blueprint if you realize your measurements were a little off halfway through.
  • Measure twice, cut once, and then measure one more time. In finance, we call this due diligence; in upholstery, it’s the difference between a perfectly snug seat and a fabric that’s pulling so tight it looks like it’s under a high-interest debt crisis.
  • Work in small, even increments. If you try to pull all the fabric tight at once, you’ll end up with wrinkles that look like a poorly folded napkin. Think of it like seasoning a sauce—add a little bit at a time, blending it in as you go to ensure total consistency.
  • Invest in quality staples, not the cheap stuff. Using low-grade fasteners is like trying to build a business on a shaky foundation; it might look fine on day one, but the moment someone sits down, the whole thing is going to crumble.
  • Mind the tension, but don’t overcook it. You want the fabric taut and smooth, but if you pull too hard, you risk tearing the fibers or warping the frame. It’s all about finding that “Goldilocks” zone—just enough pressure to hold, but not enough to cause a breakdown.

The Secret Sauce to a Successful Transformation

Don’t skimp on your “ingredients”—investing in high-quality fabric and the right tools might feel like a bigger upfront cost, but it prevents a total recipe failure and ensures your chair lasts for years to come.

Precision is everything, much like balancing flavors in a reduction; take your time with the measurements and the tension of the fabric to avoid a messy, lopsided finish.

View this project as a high-yield investment in your home; by upcycling instead of buying new, you’re practicing smart resource management while gaining a custom piece that’s worth much more than its original price tag.

The ROI of a Second Chance

“Think of reupholstering an old chair like restructuring a portfolio: you’re stripping away the outdated assets, investing in high-quality materials, and ultimately transforming something depreciated into a centerpiece that yields a lifetime of value.”

Madeline Thompson

The Final Presentation: Serving Up Your Success

The Final Presentation: Serving Up Your Success

Now that we’ve prepped our station and handled the heavy lifting, take a moment to admire what you’ve accomplished. From selecting the perfect, high-quality fabric to meticulously using your tools to secure that tension, you’ve essentially completed a full-scale kitchen renovation, but for your living room. Just like balancing a complex budget or perfecting a delicate reduction sauce, reupholstering requires a blend of precision and patience. You didn’t just patch up an old seat; you managed your resources, invested in quality materials, and executed a plan that turned something dated into something valuable. It’s all about the attention to detail that transforms a basic task into a professional-grade result.

As you sit back and enjoy your first meal in your newly transformed chair, I want you to remember the bigger picture. Whether you are mastering a new upholstery technique, scaling your career, or fine-tuning your investment portfolio, the secret ingredient is always the same: the courage to try. Don’t let the fear of a “messy kitchen” or a failed first attempt stop you from investing in yourself. Every mistake is just a lesson in seasoning, and every success is a dividend paid on your hard work. You have the tools, you have the recipe, and now, you have the confidence to create something beautiful. Bon appétit!

Frequently Asked Questions

Is it worth investing in high-end foam, or can I just stretch my budget by using what's already under the fabric?

Think of your chair’s foam like the foundation of a great risotto—you can skimp on the fancy saffron, but if your base stock is weak, the whole dish falls flat. If your current foam is crumbling or compressed, don’t try to “stretch the budget” by reusing it; it’s a bad investment that leads to a low-quality result. Invest in high-density foam now. It’s a capital expense that pays dividends in comfort for years!

How do I know if a vintage chair is a "good investment" worth the labor, or if I'm just pouring money into a broken recipe?

Think of it like evaluating a recipe before you commit to a four-hour slow roast. You have to check the “ingredients” first. Is the frame solid wood, or is it cheap particle board that’ll crumble like an overbaked biscuit? If the bones are strong, the ROI on your labor is high. But if the structure is shot, you’re just throwing good money after bad. Always audit the frame before you buy the fabric!

What should I do if I realize halfway through that I've miscalculated my fabric yardage—is there a way to pivot without starting from scratch?

Oh, the dreaded “budget overrun”! We’ve all been there—it’s like realizing you’re halfway through a reduction and realize you’re short on stock. Don’t panic; don’t scrap the whole project. Instead, pivot to a “fusion” approach. Use your remaining fabric for the seat and source a complementary, solid-colored textile for the backrest. It’s like adding a side dish to balance a main; it creates a deliberate, stylish contrast without breaking the bank.